Updated September 2026
Commercial real estate asset types are the categories of income-producing property investors can own: multifamily, manufactured housing communities, industrial, retail, self-storage, office, hospitality, RV parks, land, mixed-use, life sciences, and special-purpose properties.
Each has different demand drivers, lease structures, and risks. At Wellings Capital, we focus on five: manufactured housing communities, multifamily, small bay and flex industrial, open-air retail, and self-storage.
But the asset type is only the starting point. The operator, the purchase price, and the debt usually decide how an investment performs.
I get some version of the same question on almost every investor call: “which asset type is best right now?”
It is a fair question. It is just not the one I would start with.
I have watched a strong asset type produce a poor investment. We have also walked away from a deal in an asset type investors love. A good category does not rescue an inexperienced operator, a purchase price that is too high, debt that is too aggressive, or a business plan built on hopeful assumptions.
The question I would rather you ask is this:
Does this specific opportunity have the right operator, market, purchase basis, debt structure, business plan, and downside protection?
That is how we evaluate every deal. We invest preferred equity and JV Hybrid Equity alongside experienced operators rather than operating properties ourselves, so we are never just underwriting a building. We are underwriting the people, the market, the capital structure, and what happens if things go wrong.
This guide walks through the major commercial real estate asset types, what is happening in each one today, and how we think about them.

Asset Class vs. Asset Type: What Is the Difference?
Most people use the two terms interchangeably, and that is fine.
Technically, an asset class is a broad investment category, like stocks, bonds, private equity, or real estate. An asset type is the more precise term for the kinds of property within real estate: multifamily, self-storage, manufactured housing, retail, and so on.
Because investors search for both, this guide references both commercial real estate asset classes and commercial real estate asset types.
What is commercial real estate?
Commercial real estate (CRE) is property owned to produce income. That covers office buildings, shopping centers, warehouses, apartment communities, self-storage facilities, manufactured housing communities, hotels, mixed-use properties, medical, data centers, and more.
The simple dividing line: a single-family home you live in is not commercial real estate. A property that generates rent, lease payments, or operating revenue usually is.
Benefits of Investing in Commercial Real Estate
Commercial real estate can offer several potential advantages:
Income Potential: Commercial properties typically generate rental income or operating income. Depending on the investment structure and performance of the property, this income may be distributed to investors.
Diversification: Private commercial real estate may provide diversification outside of traditional public stocks and bonds. Investors may also diversify within real estate by investing across different asset types, geographies, operators, and strategies.
Appreciation: Commercial properties may appreciate over time if income grows, the property is improved, the market strengthens, or investor demand increases. Appreciation is not guaranteed, but it can be an important part of the total return profile.
Tax Benefits: Commercial real estate may provide tax-related benefits such as depreciation, mortgage interest deductions, and operating expense deductions. Each investor’s tax situation is different, so investors should consult their own tax advisor.
Free Download ↓
Invest with Confidence
Get your FREE Due Diligence Checklist for Passive Real Estate Investors Today!
Why Asset Type Matters, But Does Not Tell the Whole Story
Asset type shapes a lot: tenant demand, lease length, how fast rents can adjust, capital expenditure needs, financing options, operating complexity, and exit options.
But it does not make the deal.
Not long ago, we had capital raised and ready for a pair of Class A student housing properties next to a major university campus. On paper, it was the kind of deal that sells itself. Housing. Top-quality product. A major university across the street.
We did not close. Issues surfaced late in the process that we could not accept, and we walked away.
Painful, but the right call. A great asset type did not make it a great deal.
The same logic runs through every category. Multifamily benefits from housing demand, but an overleveraged apartment deal can struggle and fail. Self-storage has attractive operating features, but an oversupplied market can crush rents and occupancy. Manufactured housing benefits from affordability, but neglected infrastructure and a weak operator can sink it.
The asset type matters. The deal-level details matter more.
The Five Asset Types We Focus On
These are the categories where we currently invest alongside operators. Here is why, and what I watch in each.

1. Self-Storage
Self-storage facilities rent space to individuals and businesses on mostly month-to-month leases. Demand is driven by life events: moving, downsizing, divorce, a death in the family, military deployment, or a business that needs room for inventory.
Where it stands in 2026: self-storage is in a correction. Yardi Matrix reported national advertised rates down 1.9% year over year in August 2026. Supply is finally slowing, though. Yardi Matrix projects new supply will fall almost 19% in 2026 compared with 2025. Markets that saw heavy development are feeling the most pressure.
Though our founder, Paul Moore, wrote a book on self-storage in 2021, we are more careful here than we were a few years ago, and I have the scars to explain why.
In 2019, we invested in a ground-up self-storage development in a strong suburban Midwestern market. It is the only ground-up development deal we have ever done. The market checked nearly every box, and construction finished early and under budget.
The operator was the problem: no real asset management, slow lease-up, and expenses that ran high. (This was before we had deep experience in evaluating operators!) That experience changed how hard we press every sponsor on who actually runs asset management and how they report.
The asset type was fine. The operator was not.
Why we still like it (selectively):
Fragmented mom-and-pop ownership creates acquisition opportunities
Value-add upside through professional management, revenue management, and digital marketing
Month-to-month leases let operators adjust rents faster than most property types
Slowing new supply should help existing facilities in many markets
What we watch:
The local supply pipeline within a few miles of the property
Rent growth and lease-up assumptions
Who actually owns asset management, and how they report
How much of the sponsor’s own money is in the deal
For more, see our overview of self-storage investment funds, access our free self-storage eBook, or read Paul Moore’s book on self-storage.
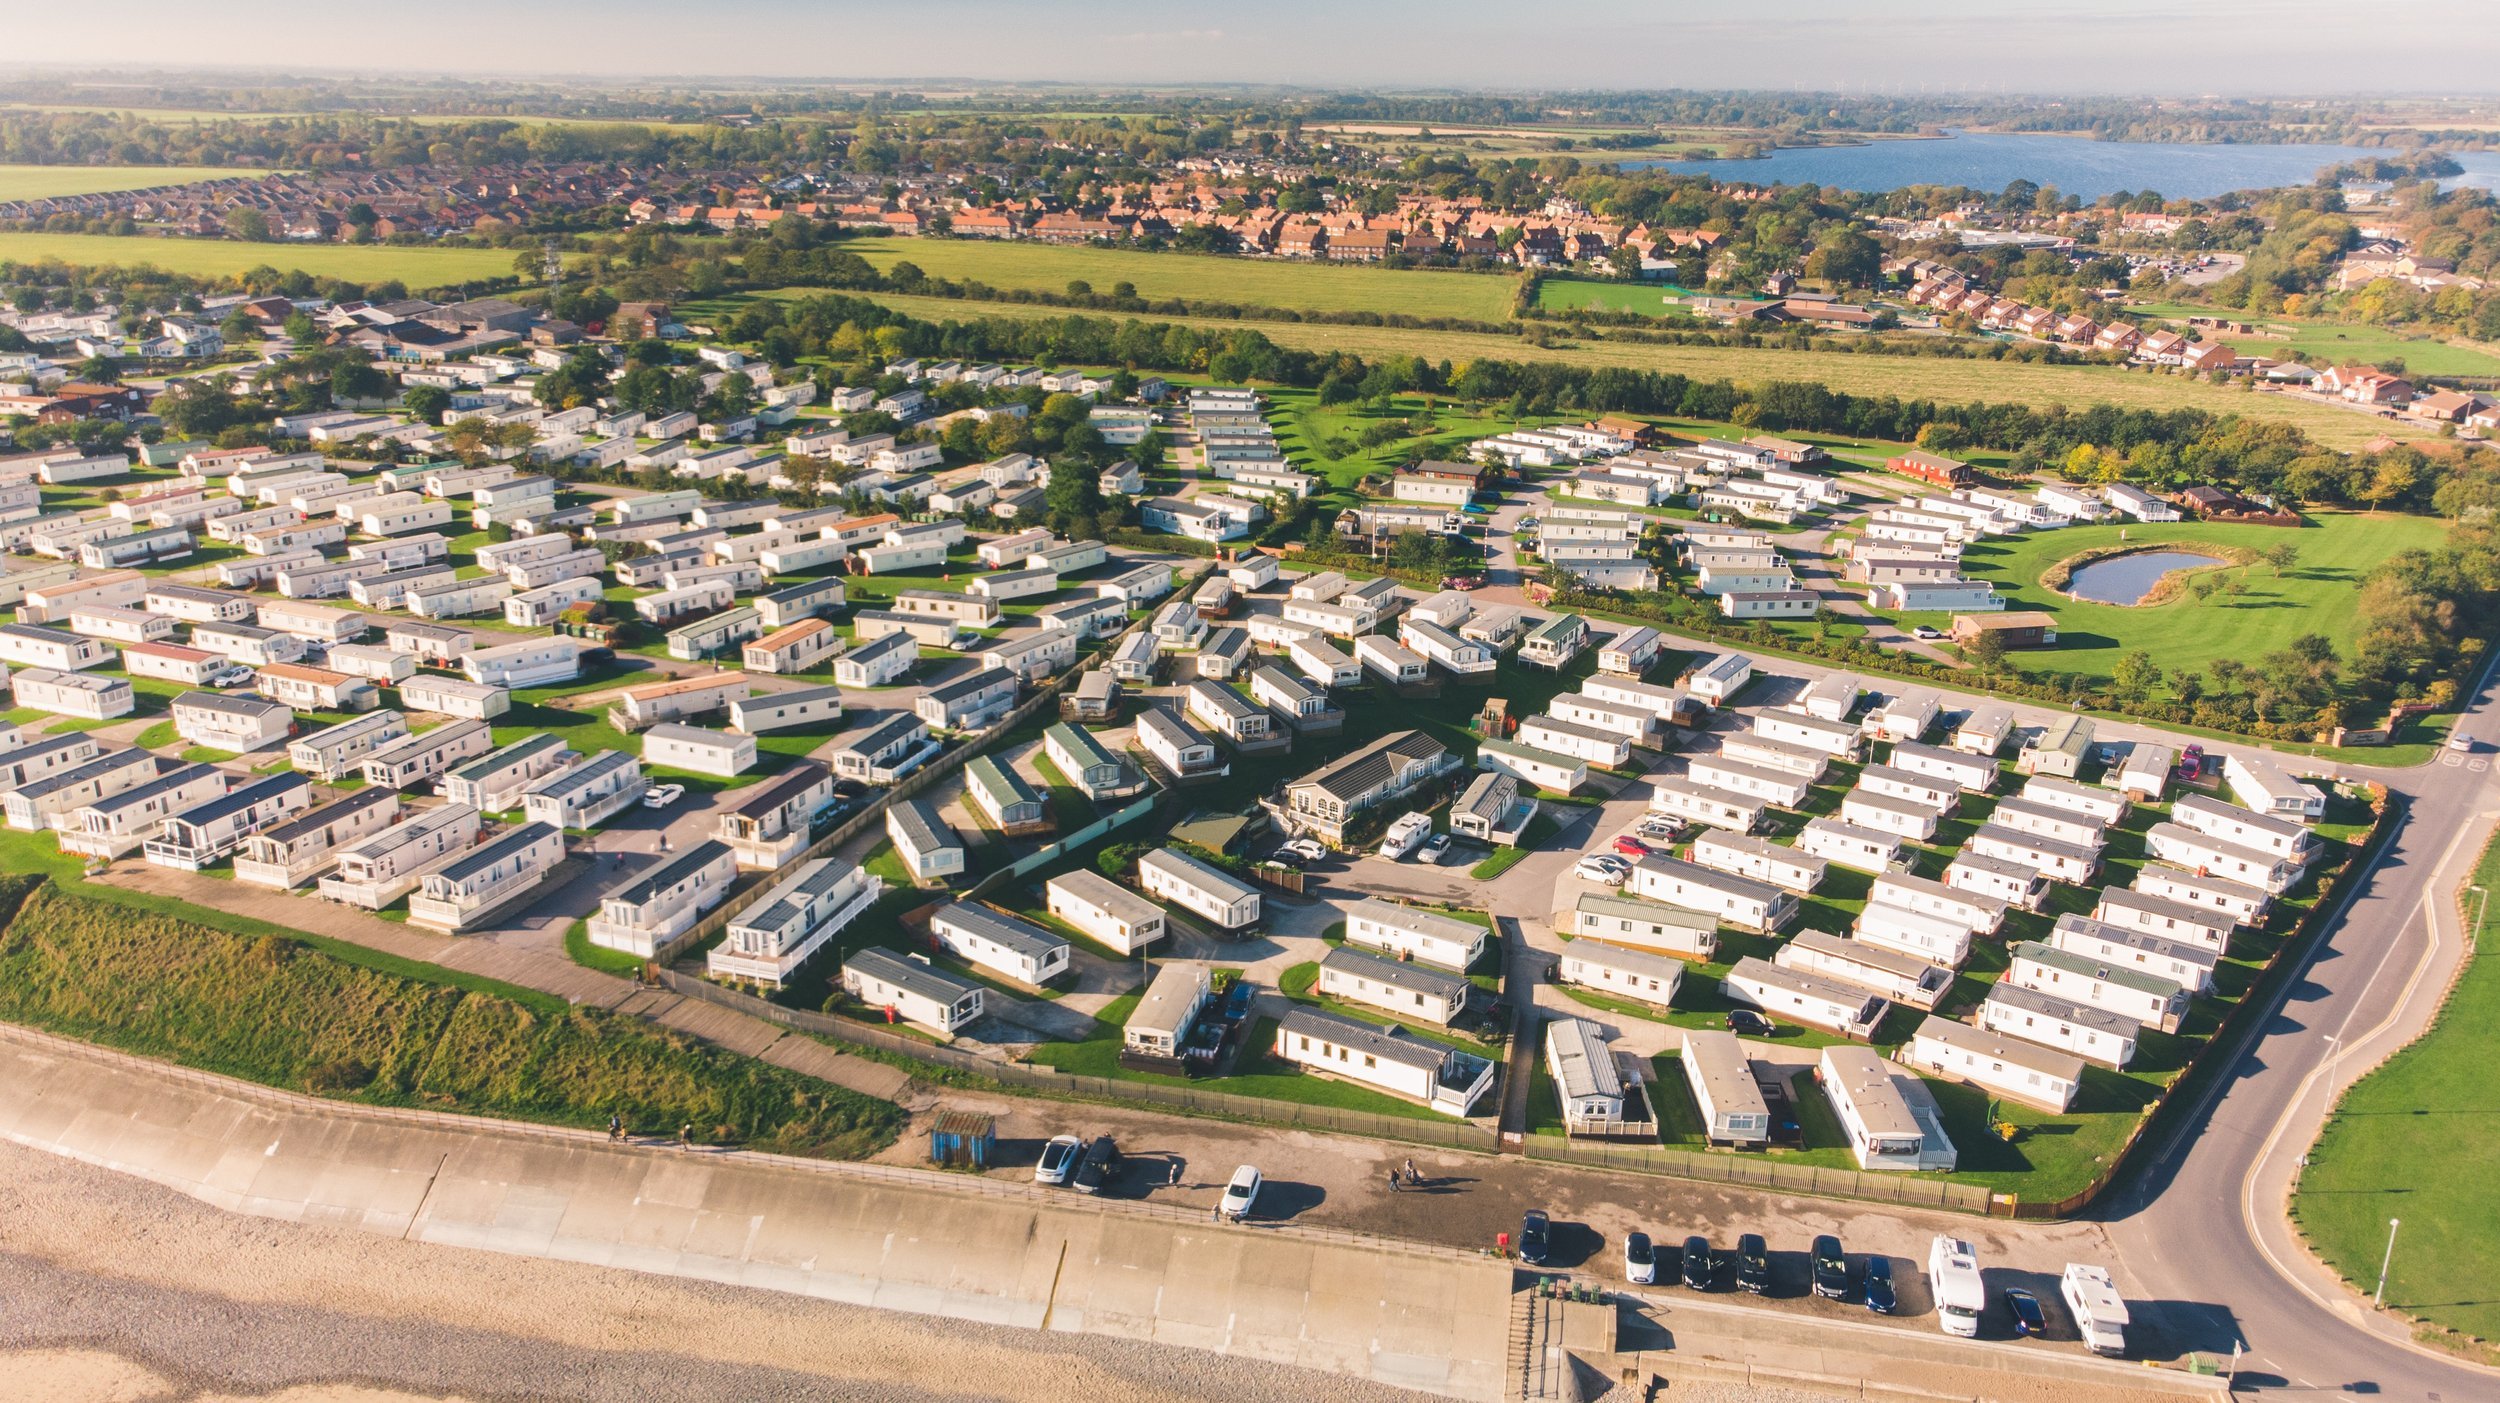
2. Manufactured Housing Communities (Mobile Home Parks)

In a manufactured housing community, residents typically own their homes and lease the land underneath from the community owner. Some communities also rent homes directly.
This asset type is tied to one of the biggest problems in American housing: affordability. As homeownership and apartment rents have climbed out of reach for many working families, a well-run community offers one of the lowest-cost housing options available.
Sophisticated investors noticed decades ago. Sam Zell built one of the largest manufactured housing community portfolios in the country, and Warren Buffett’s Berkshire Hathaway owns Clayton Homes, one of the largest manufactured home builders, as well as more than one manufactured home finance company.
Why we like it:
Very few new communities get built, largely because of zoning and local opposition, which limits new competition.
Ownership is still fragmented among mom-and-pop owners, which creates acquisition opportunities.
Moving a manufactured home is expensive, so residents tend to stay a long time.
Agency financing from Fannie Mae and Freddie Mac may be available for qualifying communities.
What we watch:
Infrastructure condition (water, sewer, roads) and deferred maintenance
Local regulation, including rent control proposals
Resident affordability and the business plan’s rent assumptions
Operator quality and resident relations
These are communities, not just financial models. Aggressive rent increases and neglected infrastructure can damage both the investment and the residents’ lives. We want operators who understand that.
For more, access our free mobile home park eBook.
3. Multifamily

Multifamily covers apartment buildings and communities with multiple rental units. It is one of the most widely owned commercial real estate asset types because it is tied to a basic need: housing.
Where it stands in 2026: multifamily is working through the tail end of a historic construction wave. According to NAHB, multifamily completions reached a 38-year high of 608,000 units in 2024. Apartment List's national multifamily vacancy index peaked at 7.3% in February 2026, the highest since it began tracking in 2017, and has since eased to 7.0% as of September 2026. The pipeline is also shrinking fast. Marcus & Millichap expects national deliveries to fall more than 34% in 2026, to about 270,000 units, the lowest total since 2014. Supply-constrained markets have generally held up better than heavily built Sun Belt metros, with NAHB noting that rents stayed strong in metros like Philadelphia while supply-rich markets weakened.
That split is exactly why the market matters as much as the asset type.
Why we like it:
Broad, needs-based demand supported by high home prices and elevated mortgage rates
Shrinking new supply that should help fundamentals in many markets
Economies of scale and a deep financing market
What we watch:
Local supply pipelines and rent growth assumptions
Property tax and insurance increases
Floating-rate debt, loan maturities, and refinancing risk
Deferred maintenance and renovation budgets
A good multifamily deal needs more than a strong housing story. It needs the right market, operator, basis, and debt. For a deeper dive, Paul Moore’s book on multifamily covers the risks in detail. Paul is the founder of Wellings Capital.
4. Small Bay and Flex Industrial
Industrial real estate includes big distribution warehouses, manufacturing facilities, and the segment we focus on: small bay and flex industrial. These are multi-tenant buildings with smaller spaces leased to contractors, trades, service companies, light manufacturers, and regional businesses.
Where it stands in 2026: industrial is really two markets. Developers spent the last cycle building large logistics boxes, and that segment has been working through elevated vacancy. Cushman & Wakefield reported that vacancy in buildings over 500,000 square feet fell to 8.1% in Q2 2026, while shallow-bay vacancy stayed at 4.8%, the lowest of any size segment.
Why we like it:
There is limited new small bay construction, because large boxes pencil better for developers
A diverse local tenant base rather than dependence on one national tenant
Tenants who tend to stay, since moving a business is disruptive and expensive
What we watch:
Tenant credit and local economic strength
Functional obsolescence (clear heights, loading, parking)
Environmental history and zoning
Leasing downtime and overpaying in competitive markets
A warehouse leased to a national tenant and a small bay building full of local plumbers and HVAC companies are completely different investments. Underwrite the one in front of you.
5. Open-Air Retail
Retail real estate ranges from enclosed regional malls to single-tenant pads to open-air neighborhood and community centers. We focus on open-air centers with daily-needs and service tenants: grocery stores, medical, restaurants, fitness, salons, and discount retailers.
Where it stands in 2026: open-air retail has quietly become one of the stronger stories in commercial real estate. Cushman & Wakefield put national shopping center vacancy at 5.9% in Q1 2026, well below its 7.4% historical average, and reported that just 10.2 million square feet of new shopping center space was delivered in 2025, an all-time low.
It is still a mistake to treat all retail as one category. A grocery-anchored center and an aging enclosed mall are not the same investment.
Why we like it:
Very little new competing supply
Service and daily-needs tenants that are harder to replace with e-commerce
Opportunity to buy existing centers below replacement cost
What we watch:
Tenant bankruptcies and store closures
Anchor tenant strength and co-tenancy provisions
Capital needs on older centers
Overexposure to discretionary retail
6. RV PArks
RV parks range from basic overnight sites to full-service destinations with utilities, amenities, and long-term guests. Demand comes from travelers, retirees, traveling workers, and outdoor recreation. They can offer flexible pricing and multiple revenue streams, but they are more operationally intensive than most investors expect.
• Seasonality and weather exposure
• Labor needs and utility infrastructure
• Dependence on tourism and transient demand
For more, access our free RV park eBook.
7. Hotels & Hospitality
Hotels and hospitality properties cater to travelers and tourists by providing lodging, dining, meeting space, and other services.
Hospitality is more operating-business intensive than many other commercial real estate asset types because revenue is often generated nightly rather than through long-term leases.
Performance may be affected by:
Business travel
Leisure travel
Local events
Tourism trends
Seasonality
Labor costs
Brand standards
Economic conditions
Competition from short-term rentals
Potential advantages may include:
Upside in strong travel markets
Daily pricing flexibility
Value-add opportunities through renovation or repositioning
Brand and management improvements
Key risks may include:
Revenue volatility
Labor and staffing pressure
High operating complexity
Seasonality
Brand-mandated renovation requirements
Financing volatility
Economic sensitivity
Hospitality can offer opportunity, but investors should understand that they are often underwriting both real estate and an operating business.
8. Land
Investing in undeveloped land may offer investors the opportunity to participate in future development projects or land banking strategies.
Land investments require patience and careful analysis. Unlike income-producing properties, land may not generate current cash flow. The investment thesis often depends on future development, rezoning, population growth, infrastructure improvements, or market appreciation.
Important factors include:
Zoning
Entitlements
Infrastructure access
Environmental conditions
Market demand
Holding costs
Development feasibility
Exit options
Land values may appreciate if population growth, development demand, or scarcity increase. However, land carries meaningful risks, including entitlement delays, environmental issues, lack of income, market changes, and uncertain exit timing.
Land can be profitable, but it is often more speculative than stabilized income-producing commercial real estate.
9. Mixed Use
Mixed-use properties combine multiple property types within one project. For example, a property may include apartments over retail, office with retail, or residential and commercial uses within the same development.
Mixed-use developments are often found in urban and suburban markets seeking walkability, convenience, and a live-work-play environment.
Potential advantages may include:
Multiple income sources
Strong location appeal
Walkable environments
Diversification within a single property
Potential synergies between uses
Key risks may include:
More complex operations
Different tenant types with different needs
Higher construction or redevelopment complexity
Zoning and entitlement risk
More complicated financing
Uneven performance between property components
Mixed-use properties require careful analysis because success depends on how the different uses work together. A strong apartment component does not automatically solve weak retail demand, and a strong location does not eliminate operational complexity.
10. Office
Office buildings provide workspace for businesses and professionals, ranging from small companies to large corporations.
The office sector is influenced by job growth, corporate expansion or contraction, remote work, hybrid work, tenant preferences, building quality, location, and capital market conditions.
Office has become more challenging in many markets because of remote work trends, tenant downsizing, higher vacancy, and financing pressure. That does not mean all office investments are bad, but it does mean investors should approach office with caution and strong market-specific analysis.
Important factors include:
Tenant demand
Lease rollover
Tenant credit
Building quality
Location
Amenities
Capital expenditure needs
Tenant improvement allowances
Local vacancy
Financing terms
Class A office buildings in strong locations may perform differently than older suburban office buildings with weak tenant demand. Investors should avoid making broad assumptions about office as a single category.
Key risks may include:
Weak tenant demand
High capital expenditure needs
Leasing costs
Tenant improvement allowances
Refinancing risk
Obsolescence
Location-specific vacancy pressure
Office investing requires a clear understanding of the local market and the property’s competitive position.
11. Life Sciences
Life sciences properties include research laboratories, biotech facilities, pharmaceutical manufacturing facilities, and specialized spaces used by healthcare, research, and scientific companies.
The life sciences sector is driven by innovation, scientific research, healthcare demand, and the need for specialized facilities.
Potential advantages may include:
Specialized tenant demand
Long-term tenant relationships
High build-out costs that may increase tenant stickiness
Proximity value near universities, hospitals, research hubs, and healthcare clusters
Key risks may include:
Specialized build-out requirements
Regulatory considerations
Tenant concentration
Limited alternative use
High capital costs
Industry-specific volatility
Life sciences real estate can be attractive in the right markets, but investors must understand the tenant base, specialized property requirements, and potential re-use limitations if a tenant leaves.
12. Special Purpose
Special-purpose properties are built or configured for a specific use. These may include data centers, hospitals, educational facilities, churches, schools, theaters, amusement parks, sports complexes, cold storage facilities, car washes, senior housing, and other niche properties.
Potential advantages may include:
Niche demand
Specialized tenant relationships
Less direct competition in some markets
Potentially strong income if the tenant and use are durable
Key risks may include:
Limited alternative use
Smaller buyer pool at exit
Specialized maintenance needs
Regulatory considerations
Tenant or operator dependency
Higher re-leasing risk
Special-purpose properties require extra scrutiny because value may depend heavily on a specific use, tenant, or operator.
These investments are not automatically bad, but they often require deeper due diligence and a clear understanding of what happens if the original business plan does not work.
How Wellings Capital Thinks About Commercial Real Estate Asset Types
At Wellings Capital, we believe the asset type is important, but it is not enough.
We are not trying to invest in a category simply because it is popular. We are trying to evaluate whether a specific opportunity has the right combination of operator quality, market fundamentals, purchase basis, capital structure, downside protection, and alignment of interests.
That is why operator selection is central to our process.
An experienced operator may reduce risk by buying at a reasonable basis, using appropriate leverage, managing expenses, maintaining reserves, communicating clearly, and executing a realistic business plan.
A weak operator can create problems even in a strong asset type.
When we evaluate opportunities, we consider factors such as:
Operator experience
Team depth
Track record
Market fundamentals
Property condition
Business plan assumptions
Debt terms
Capital structure
Exit assumptions
Downside scenarios
Alignment of interests
Reporting and communication practices
The goal is not simply to find a good asset type. The goal is to find an investment opportunity where the asset, operator, market, structure, and risk profile make sense together.
This is the backbone of our 26-step due diligence process. We also invest through preferred equity and JV Hybrid Equity, because where we sit in the capital stack is part of the downside protection. If those terms are new, start with Preferred Equity in Private Real Estate: Terms and Definitions and The Waterfall in Commercial Real Estate and Private Equity.
If you have any questions, please email us at invest@wellingscapital.com or use this link to set up a call.
Frequently Asked Questions
-
No investment is completely safe. Commercial real estate may offer income potential, diversification, appreciation potential, and tax benefits, but it also carries risk.
Risks may include market changes, tenant turnover, rising expenses, interest rate changes, refinancing risk, poor operator execution, declining property values, and the possible loss of principal.
Investors should carefully review the offering documents, understand the risks, and consult their own advisors before investing.
-
The four traditional commercial real estate asset classes are:
Multifamily
Industrial
Retail
Office
Private real estate investors may also evaluate other asset types such as self-storage, manufactured housing communities, RV parks, hospitality, land, mixed-use, life sciences, medical office, senior housing, and special-purpose properties.
-
There is no universally safest real estate asset class.
Some investors view needs-based asset types, such as multifamily or manufactured housing communities, as more stable because they are tied to housing demand. Others may favor properties with long-term leases, strong tenants, or conservative financing.
However, safety depends on more than the asset class. The operator, market, debt structure, purchase price, reserves, tenant demand, and business plan all matter.
-
Risk varies by deal, but asset types with more operating volatility, specialized use, uncertain demand, high leverage, or limited exit options may carry greater risk.
Hospitality, speculative development, land, certain office properties, and special-purpose properties can require especially careful analysis.
That does not mean these investments are always bad. It means investors need to understand the risks and the assumptions behind the business plan.
-
Residential real estate is generally the largest real estate category overall. Within commercial real estate, multifamily is often one of the largest and most widely owned asset types because of the size of the rental housing market.
However, the “largest” asset class is not automatically the best investment. Investors should focus on risk-adjusted returns, operator quality, market fundamentals, and structure.
-
Investors may define the pillars differently, but three core pillars are:
Market fundamentals
Operator execution
Capital structure
A strong market can help support demand. A strong operator can execute the business plan. A conservative capital structure can help protect the investment if conditions change.
If one of these pillars is weak, the overall risk profile may increase.
-
Operator selection matters because the operator is responsible for executing the property-level business plan.
Even an attractive property type can underperform if the operator lacks experience, uses too much leverage, underestimates expenses, overestimates rent growth, or fails to manage the property effectively.
In private real estate, investors are not just investing in a property type. They are also investing in an operator, a structure, a market, and a business plan.
DISCLAIMER: Past performance is not indicative of future results. There is no guarantee that any forecasts or projections will be achieved. Any investment involves significant risk, including the possible loss of principal. Investors should carefully consider the investment objectives, risks, charges, and expenses of any Wellings Capital Management, LLC (“Wellings”) investment program. Offering documents containing this and other important information are available by calling 800.844.2188, emailing invest@wellingscapital.com, or visiting wellingscapital.investnext.com.
The information in this article is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any securities in any jurisdiction where such an offer or solicitation would be unlawful. Wellings does not provide tax, legal, or accounting advice. Investors should consult their own advisors regarding any investment. Information and any opinions contained in this article have been obtained from sources that we consider reliable, but we do not represent that such information and opinions are accurate or complete and thus should not be relied upon as such.