Updated September 2026
Is industrial real estate a good investment in 2026? For small bay and flex industrial, we believe it can be. National industrial vacancy fell to 6.9% in Q2 2026, and shallow-bay vacancy held at 4.8%, the tightest of any size segment, according to Cushman & Wakefield. Very little small bay space is being built, because most new construction has gone to big-box warehouses, according to CBRE. Large warehouses are a different market, so the segment and the operator matter more than the headline.
Wellings Capital and its affiliates have been investing in commercial real estate, including mobile home parks and self-storage, for years. We added industrial real estate over the last several years, and this asset type is providing meaningful risk-adjusted returns for investors in three of our funds.
He may have been exaggerating. But it didn’t seem like it.
I was meeting with a Philadelphia industrial developer for breakfast, and he stated that no Class B small bay/flex industrial real estate is available to rent or buy in his county.
I hear this everywhere, from Phoenix to Florida and many points between. Strategically located small bay/flex industrial space is in extremely high demand.
But that doesn’t mean it’s a good investment.
Internet stocks were also in high demand in 1999, and we know how that ended. In this article, we’ll explore the viability of the industrial real estate asset type, and I’ll share some things to look for as you evaluate an investment.
What Is Industrial Real Estate?
Industrial real estate encompasses facilities dedicated to manufacturing, production, research and development, storage, and distribution. This may include manufacturing plants, warehouses/storage facilities, e-commerce centers, land/lots for outdoor storage and parking, flex industrial (office space in the front, warehouse in the back), and showrooms. Some industrial real estate is also called “logistics” real estate. Industrial real estate assets are typically located adjacent to key transportation hubs such as seaports, highways, rail junctions, and airports.
Some industrial assets are built to suit internally or for lease. Some are built on spec, with the hope of finding appropriate tenants. Many are repurposed from a previous use to a newer one.
As a side note, I wrote a book on self-storage where I highlighted the strategy of converting older industrial or retail buildings to self-storage. Our firm, Wellings Capital, has invested in conversions like this.
Why Has Industrial Real Estate Grown So Fast?
The online revolution and the rapid growth of the entrepreneurial economy have spurred significant growth in the industrial real estate sector. The proliferation of e-commerce, with its broad supplier base and heightened customer demands, has strained the nation’s warehousing and logistics capabilities.
E-commerce reached about 17% of U.S. retail sales in Q2 2026, according to the U.S. Census Bureau, up from about 10% before the pandemic.
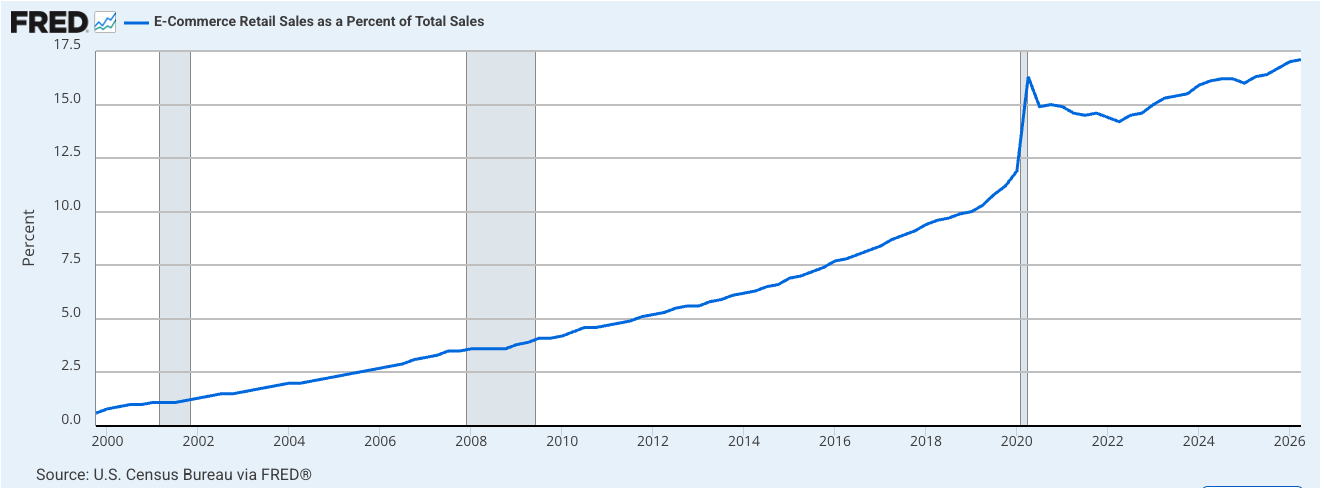
One might expect a marginal impact on industrial, since e-commerce only replaces retail sales. But e-commerce uses more space than traditional distribution. Cushman & Wakefield has estimated that e-commerce fulfillment requires three to four times the logistics space of traditional retail distribution, because online orders require more inventory, more product variety, and parcel shipping instead of pallets.
Other forces have added to demand. Self-storage and apartment developers have absorbed land that might otherwise be available for industrial development. Manufacturers and supply chains are building facilities closer to consumers for fast delivery. And after the supply chain disruptions of recent years, many companies now stock more goods onsite and build redundancy into their systems.
Where Industrial Real Estate Stands in 2026
After a record construction wave, the industrial market is tightening again. Here is the national picture from Cushman & Wakefield’s Q2 2026 report:
Vacancy is falling. National industrial vacancy fell to 6.9% in Q2 2026.
Demand is picking up. Net absorption climbed to 62.1 million square feet in the quarter.
Big boxes are recovering, but still loose. Vacancy in buildings over 500,000 square feet has fallen 300 basis points from its late-2024 peak, to 8.1%.
Small bay remains the tightest segment. Shallow-bay vacancy edged modestly higher but held at 4.8%, the lowest of any size segment.
Rents are still growing, more slowly. Asking rents rose 2.9% year over year, to $10.32 per square foot.
CBRE reported the same turn: industrial vacancy declined in Q2 2026 for the first time since Q2 2022, driven by strong leasing and a significant slowdown in construction.
Is It Too Late to Invest in Industrial Real Estate?
“If rental rates and occupancy have surged for years, maybe I missed the boat. Perhaps the natural supply and demand shift means this is not the ideal time to invest in industrial real estate.”
It’s a fair question. Here’s how I think about it.
Real estate development retracts in slowdowns. Interest rates often rise on the front edge of slowdowns, and projected returns on development deals become uncertain. The result is decreasing new supply.
That is largely what happened in industrial. Developers delivered a wave of big-box space, then pulled back sharply. As deliveries slowed, vacancy peaked and began to fall again. For small bay, which developers mostly skipped, the supply picture was tight to begin with.
So no, I don’t think the boat has sailed for small bay. But the easy money in industrial is gone. What matters now is buying the right asset at the right price and operating it well. That brings me to our strategy.
How to Pick a Winner in Almost Any Economy
Speculative real estate development creates big winners and big losers as economies expand and contract. This is not my favorite way to invest.
My firm focuses on risk-adjusted returns, which weigh not just raw profits, but how much risk investors take to obtain those profits.
I’m in my third decade as a real estate investor, and I’ve learned a “secret” to successfully accelerate risk-adjusted returns. It’s not really a secret, but it seems like one since it is more frequently discussed than implemented.
Warren Buffett has done quite well for his investors with a similar strategy, value investing, buying whole businesses or shares of businesses for less than they are worth. According to Berkshire Hathaway's 2025 shareholder letter, $100 invested in Berkshire in 1964 grew to about $6.1 million by the end of 2025, compared with about $46,000 in the S&P 500. Berkshire could lose about 99% of its value and still be ahead. Think about that.
So, what is this so-called secret?
Acquire assets with significant intrinsic value, mine that value to increase profits faster than interest rate hikes and expanding cap rates can erode it, then hold the asset until a favorable point in the economic cycle.
Intrinsic value refers to potential not tapped by the current owner. Identifying and unlocking it provides a powerful opportunity to increase profits, value, and investor wealth.
Let’s detour for a quick commercial real estate value primer. While residential real estate value is based on comparable properties, commercial real estate is based on net income (NOI) and capitalization (“cap”) rates.
CRE Value = Net Operating Income ÷ Cap Rate
The cap rate is the market’s view of the expected unleveraged return for a given asset at a given location and time. Cap rates tend to expand when interest rates rise or the economy weakens, which pushes values down. For a deeper dive, see What Is a Cap Rate? Understanding Cap Rates in Commercial Real Estate.
NOI is largely under the operator’s control. The cap rate mostly is not. So in any economy, the operator’s goal is to find assets with intrinsic value and extract that value by increasing income. If the operator increases income enough and isn’t forced to sell, investors may be largely insulated from the value-shrinking pull of expanding cap rates in bad economies. In strong economies, when cap rates compress, NOI growth accelerates the gains.
AN EXAMPLE OF INTRINSIC VALUE
One of our self-storage investments in Colorado had a large vacant warehouse attached to the facility. Our operating partner cleaned up the space, performed deferred maintenance, then leased it to three tenants.
That warehouse lease raised the property’s value from its purchase price of about $11 million to almost $20 million, assuming a 6% cap rate. The equity in the deal was just under $5 million. This is a great example of mining intrinsic value, and we were happy to be the largest investor in this deal.
Free Download ↓
Invest with Confidence
Get your FREE Due Diligence Checklist for Passive Real Estate Investors Today!
What Is Small Bay Industrial?
The industrial asset class can be divided into three segments: small bay, mid bay, and large bay (often called big box). “Light industrial” usually describes small bay facilities, which are also known as small bay warehouses, flex industrial, or industrial parks. This is our favorite industrial strategy.

Small bay industrial units typically range from 1,500 to 15,000 square feet, and often 25% to 30% of each unit is office space. A property might have anywhere from 3 to 15 separate buildings. Zoning is usually flexible, allowing light manufacturing, distribution, construction, business services, and technology users. Leases are typically renewed for three to five years.
Because small bay properties are usually infill locations with many small tenants, they have an inherently diversified tenant base. A small bay park full of local plumbers, HVAC companies, and contractors is a very different investment from one big warehouse leased to a single national tenant.
Why Small Bay Industrial Is Undersupplied
Shallow-bay vacancy has run below the overall industrial vacancy rate since 2017, because most new construction went to big-box warehouses, according to CBRE. With little new development over the past two decades, most shallow-bay inventory is in older buildings.
That is exactly where mom-and-pop owners leave value on the table. I was surprised to learn that many industrial parks are owned by individuals who lack the skills, desire, or resources to improve the property, increase cash flow, and maximize value.
These assets often suffer from poor management, outdated layouts and color schemes, old HVAC and windows, leaky roofs, ugly landscaping, inadequate signage, and poorly maintained parking lots. These often-absentee owners typically have significant vacancies and below-market rents. Yet no individual tenant has the negotiating power to convince the landlord to make changes. We see all of this as intrinsic value potential.
Here is a graphic to help you visualize improvements at a light industrial park:

What Are the Risks of Small Bay Industrial?
Small bay has strong fundamentals, but it is not risk-free. Here is what we watch:
Tenant credit and local economy. Small local businesses are more exposed to a regional downturn than national tenants.
Functional obsolescence. Low clear heights, poor loading, and limited parking can make older buildings hard to lease.
Environmental history and zoning. Past industrial uses can leave contamination, and zoning determines who can lease the space.
Overpaying. Growing investor interest in small bay has pushed prices up in competitive markets, so disciplined underwriting matters more than ever.
That is why operator selection sits at the center of our 26-step due diligence process. For how industrial compares with other property types, see Commercial Real Estate Asset Types and Asset Classes: A Complete Guide.
Frequently Asked Questions
-
Small bay industrial consists of multi-tenant buildings with smaller units, typically 1,500 to 15,000 square feet, leased to local businesses such as contractors, trades, and light manufacturers. Big box industrial consists of large warehouses, often over 500,000 square feet, usually leased to a single national tenant for distribution. The two segments have different supply, demand, and risk profiles.
-
Flex industrial space combines office and warehouse space in one unit, typically with office space in the front and warehouse or light manufacturing space in the back. It is popular with small businesses that need both a customer-facing area and room for inventory, equipment, or production.
-
Developers built mostly large warehouses during the last construction cycle because big buildings are more economical to develop. Very little new small bay space was added, while demand from small businesses stayed strong. In Q2 2026, Cushman & Wakefield reported shallow-bay vacancy of 4.8%, compared with 8.1% for buildings over 500,000 square feet.
-
Investors typically earn returns from rental income and from increasing the property’s value. Value often comes from raising below-market rents, leasing vacant units, improving management, and upgrading the property. Because commercial property value is based on net operating income, higher income can lead to a higher property value.
-
Look at the local economy and tenant mix, the condition and layout of the buildings, environmental history, zoning, and the purchase price relative to replacement cost. Just as important is the operator: their experience with small bay, their leasing and management plan, and how much of their own money is in the deal.
Conclusion
Is industrial real estate a good investment in 2026 and over the next 5 to 10 years? For small bay industrial, bought at the right price and run by the right operator, we believe it is, for us and our investors.
If you have any questions, please email us at invest@wellingscapital.com or schedule a call.
DISCLAIMER: Past performance is not indicative of future results. There is no guarantee that any forecasts or projections will be achieved. Any investment involves significant risk, including the possible loss of principal. Investors should carefully consider the investment objectives, risks, charges, and expenses of any Wellings Capital Management, LLC (“Wellings”) investment program. Offering documents containing this and other important information are available by calling 800.844.2188, emailing invest@wellingscapital.com, or visiting wellingscapital.investnext.com.
The information in this article is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any securities in any jurisdiction where such an offer or solicitation would be unlawful. Wellings does not provide tax, legal, or accounting advice. Investors should consult their own advisors regarding any investment. Information and any opinions contained in this article have been obtained from sources that we consider reliable, but we do not represent that such information and opinions are accurate or complete and thus should not be relied upon as such.